I recently met up with a friend deep in the throes of buying his first home with his wife. Aside from the renovation loan he was taking and contractor quotes he was drowning in, the most pressing expense category on his mind surprised me: furniture.
Interestingly, my friend’s woes weren’t about what furniture to buy. They were about how he should buy them. Buying a new sofa or home entertainment system is a major expense, and my friend wanted to earn the most out of the transaction, whether in the form of miles, cashback or rewards points.
But here’s the catch: big-ticket spending doesn’t always play nicely with credit card rewards. You might hit a monthly rewards cap before the full amount is even billed, or worse—discover the purchase didn’t qualify for the bonus earn rate at all.
That’s where having the right credit card comes in.
In this guide, we spotlight a curated list of credit cards—both miles and cashback options—that help you sidestep these issues. Whether you’re team miles or firmly in the cashback camp, these cards can help you make your next major buy a lot more rewarding.
[ms-toc title="Best credit cards for furniture and electronics"]
1. Summary: Best cards for buying furniture, electronics and other big ticket items
These cards are the best options I found that let you earn miles or cashback on at least $1,000 worth of spending in a month. Some even have no cap on the amount of spending you can earn bonus rates on—get the details below.
Card | Reward type | Highest earn rate | Bonus spend category | Minimum spend | Maximum spend (before your bonus is capped) |
Miles | 2.4 mpd | Online shopping, dining, food delivery, online travel, transport | $1,000 annual spend on Singapore Airlines, Scoot and KrisShop | No cap | |
Miles | 4 mpd | Online purchases (local and overseas) | None | $1,000/month | |
Miles | Up to 6 mpd | Shopee, Lazada, Taobao, TikTok Shop, Watsons, department stores, retail | None | $1,000/month at 6 mpd; $1,110/month at 4 mpd | |
Miles | 4 mpd | Online purchases; department, clothing, shoe, and luggage stores | None | $1,000/month | |
Miles | 4 mpd (up to 8 mpd) | Online and contactless spend on shopping, dining, and travel | None | ~$1,000/month ($1,200 at 8 mpd) | |
Miles | 2 mpd | Online purchases | None | $1,000/month | |
Cashback | 5% | Online, groceries, transport | $500/month | $12,000/year | |
Cashback | 3% (first $5,000) | All spend | None | $5,000 (first 6 months), then 1.5% uncapped | |
Cashback | 2.5% | All spend | >$2,000/month | $2,800/month | |
Cashback | 2% | All spend | None | $10,000/month |
Miles and rewards cards
2. KrisFlyer UOB Credit Card (2.4 mpd, no spend cap)
- Maximum earn rate: 2.4 mpd (you can earn 3 mpd, but this rate isn’t applicable to buying furniture)
- Bonus spend category: Online shopping (e.g. Shopee, Lazada, Taobao), dining, food delivery, online travel, transport
- Minimum spend: $1,000/year on Singapore Airlines, Scoot or KrisShop (to unlock 2.4 mpd)
- Monthly spend cap: None
Looking for a miles card that rewards online shopping with no spend cap? The KrisFlyer UOB Credit Card gives you up to 2.4 miles per dollar on categories like online shopping, dining, online travel bookings, and transport, as long as you also spend at least $1,000 a year with Singapore Airlines, Scoot or KrisShop.
Key platforms like Shopee, Lazada, and Taobao qualify—as long as your transaction is processed under the right Merchant Category Code (MCC). Yup, that means 2.4 miles per dollar on furniture you order from these online shopping platforms.
Unlike some cards that limit your rewards each month, this card has no cap, so you can fully earn rewards on even the priciest furniture splurges.
Here's the breakdown of the KrisFlyer UOB Credit Card’s earn rates:
- 3 mpd on spend with Singapore Airlines, Scoot, KrisShop, Kris+, and Pelago
- 2.4 mpd on eligible spend in bonus categories like online shopping and dining (with at least $1,000 annual spend on Singapore Airlines, Scoot or KrisShop)
- 1.2 mpd on all other transactions
A key perk: your miles are credited directly to your KrisFlyer account, with no conversion fee. Just note that only the base 1.2 mpd lands monthly. The bonus miles are credited after your card membership year ends, so a furniture splurge today may take months to fully show up in your account.
Plus, you’ll enjoy Kris+ and Scoot perks, as well as savings on rides with Grab, adding more value if you’re travelling or shopping locally.
(S24-0487) Small (1).jpeg)
- on Singapore Airlines, Scoot, KrisShop, Kris+ and Pelago purchases
- S$1 = 3 Miles
- on dining, food delivery, online shopping, online travel and transport spend
- S$1 = Up to 2.4 Miles
- on all other spend
- S$1 = 1.2 Miles
3. DBS Woman’s World Card (4 mpd, up to $1,000/month spend)
- Maximum earn rate: 4 mpd (10X Points)
- Bonus spend category: Online purchases (local & overseas)
- Minimum spend: None
- Monthly spend cap: $1,000
The DBS Woman’s World Card offers an attractive 4 miles per dollar on online purchases—but there’s a small catch: rewards are awarded in blocks of $5 per transaction, so odd-amount transactions can lose you a little on the base points.
Here’s how the rewards break down:
- For every $5 spent online, you get 10 DBS Points (4 mpd)
- For overseas spend: 3 DBS Points per $5 (1.2 mpd)
- All other spend: 1 DBS Point per $5 (0.4 mpd)
The $1,000 monthly cap on bonus points (down from $1,500 before Aug 2025) means it's best for covering the first $1,000 of a bigger online buy. Pair it with an uncapped card like the KrisFlyer UOB Credit Card for the rest.
It’s also worth noting the minimum income requirement is $80,000, so it’s not entry-level. Still, for those who qualify, it's one of the simplest 4 mpd cards for online shopping. Just factor in the 3.25% foreign currency fee if you're buying from overseas sites.

- on Online Purchases
- S$5 = 10 DBS Points (equivalent to 4 Miles per S$1)
- on Overseas Purchases
- S$5 = 3 DBS Points (equivalent to 1.2 Miles per S$1)
- on all Other Purchases
- S$5 = 1 DBS Point (equivalent to 0.4 Miles per S$1)
4. OCBC Rewards Credit Card (6 mpd, up to $1,110/month spend)
- Maximum earn rates and categories:
- 6 mpd at Shopee, Lazada, Taobao, TikTok Shop, and Watsons (until 31 Mar 2027)—see the full list in their terms and conditions
- 4 mpd on other eligible online and retail spend
- Minimum spend: None
- Monthly spend cap:
- $1,000 at 6 mpd (5,000 promo OCBC$)
- $1,110 at 4 mpd (10,000 bonus OCBC$)
The OCBC Rewards Credit Card is a strong contender for anyone buying big-ticket items like furniture or electronics online. With up to 6 miles per dollar on Shopee, Lazada, Taobao, and TikTok Shop, and 4 miles per dollar (10 OCBC$ per $1) on other eligible spend, it's ideal for large purchases from merchants like Taobao, Lazada, and Shopee—all of which are explicitly whitelisted. Just note that payments made via ShopeePay won't earn any OCBC$, and grocery purchases on Shopee and Lazada don't earn bonus OCBC$.
Just like some other high-earning rewards cards, this one also awards points in blocks of $5 spend. For every $5:
- 5 OCBC$ (base) are awarded automatically
- 45 OCBC$ (bonus) are added by the end of the next calendar month
- That’s a total of 50 OCBC$ per $5, equivalent to 4 mpd
However, the bonus is capped at 10,000 OCBC$ per month, so you’ll only enjoy the full 4 mpd on about $1,110 of spending. After you hit that, you’ll drop back down to base earnings—just 0.4 mpd.
Until 31 Mar 2027, OCBC is giving an extra 5 OCBC$ per $1 (2 mpd) at Shopee, Lazada, Taobao, TikTok Shop, and Watsons, on top of the regular bonus. That works out to 6 mpd on your first $1,000 at these merchants each month. If you're buying furniture off Taobao, this is the card to beat.
You can exchange your OCBC$ for:
- Miles (10 OCBC$ = 4 miles)
- Cash rebates ($10 for 3,600 OCBC$)
- Vouchers or lifestyle products
.png)
- for every S$1 spent at Watsons and certain online shopping platforms
- Earn 15 OCBC$ (equivalent to 6 air miles)
- on All Other Spend
- S$1 = 1 OCBC$
- Rewards to Miles Conversion
- 10 OCBC$ = 4 Miles
Get $200 Cash or 3,000 SmartPoints (enough to redeem an AirPods 5 worth S$219) when you apply and spend a min. of S$400 within 30 days! T&Cs apply.
5. Citi Rewards Card (4 mpd, up to $1,000/month spend)
- Maximum earn rate: 4 mpd (10X Points)
- Bonus spend category: Online purchases (excluding travel and mobile wallet transactions), plus purchases at department stores and clothing, shoe, and luggage stores
- Minimum spend: None
- Monthly spend cap: $1,000 (9,000 bonus points per statement month)
If you're furnishing a new place or upgrading your home electronics, chances are you're shopping online—Lazada, Taobao, and other major platforms included. That's exactly where the Citi Rewards Card shines.
This card gives you 10X Rewards Points (or 4 miles per dollar) on eligible online transactions—so Taobao, Lazada, and other e-commerce checkouts all count. It also earns 10X on in-store purchases at department stores, which comes in handy if you're picking up a TV or appliances in person. That said, buying in person at a dedicated furniture or electronics store won't earn 10X. Buy online instead (even from the same retailer) or at a department store.
Points are also calculated per $1 rather than in $5 blocks, so odd-amount purchases don't lose you much. Best of all, there's no minimum spend, and you can use your points to offset purchases with Citi Pay with Points, or redeem them for miles, cash rebates, vouchers, or products via the Citi ThankYou Rewards catalogue. If you opt for miles, 10 points convert to 4 miles. Points are valid for up to 5 years.
Pair the Citi Rewards Card with the Instarem Amaze Card to earn 4 mpd on in-person spending too. Just note that Amaze now charges a 1% fee on local SGD spend, so it's only worth it on larger transactions. Find out more in my review of the best credit cards to pair with the Amaze Card.
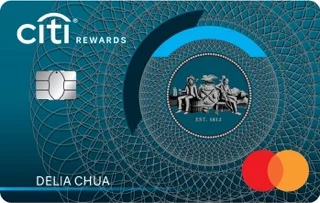
- on Online Grocery, Food Delivery, Ride-Hailing
- S$1= 10X Points
- for in-store shopping purchases at Department Store, Clothing Stores
- S$1= 10X Points
- for all other purchases
- S$1= 1X Point
Snap up baseline gifts: be among the first 200 approved applicants spending S$500 to enjoy S$450 Upsized Cash or a S$500 Amazon.sg Gift Card, or still grab S$400 Cash or 6,140 SmartPoints (use SmartPoints earned to redeem the latest Apple products on our Rewards Store) if you come after.
But the real treat? Dive into spooktacular Halloween rewards with MoneySmart! Each day, the first 10 fastest claimants snatch exclusive Flash Deal prizes—from iPhone 18 Pro, MacBook Neo, Switch 2, PS5 and more—on top of your baseline reward! T&Cs apply.
6. HSBC Revolution Card (4 mpd, up to $1,000/month spend)
- Maximum earn rate: 4 mpd (10X Points); up to 8 mpd (20X Points) if you keep at least $50,000 in an HSBC Everyday Global Account
- Bonus spend category: Online and contactless spend on shopping, dining, travel, ride-hailing, taxis, and memberships, locally and overseas
- Minimum spend: None
- Monthly spend cap: $1,000 (9,000 bonus points per calendar month); $1,200 at 8 mpd (22,800 bonus points)
The HSBC Revolution Card isn't just for online shoppers anymore. Since 1 Apr 2026, you'll earn 10X HSBC Reward Points (equivalent to 4 miles per dollar) on eligible online and contactless spending—including electronics stores, camera shops, marketplaces, and department stores. That makes it one of the few miles cards here that rewards you for tapping to pay at an electronics store (inserting your card won't count). Furniture is trickier, though: dedicated furniture stores aren't on HSBC's eligible list, so buy through an online marketplace or a department store instead.
Here's the catch: bonus points are capped at 9,000 per calendar month, or about $1,000 in eligible spend, after which you'll earn just 0.4 mpd. Keep at least $50,000 in a sole HSBC Everyday Global Account, though, and you'll earn 20X (8 mpd) on up to about $1,200 a month. Also note that purchases split with HSBC's 0% Instalment Payment Plan or PayLater Instalment Plan earn no points.
There's no minimum spend and no annual fee, but you'll need an annual income of at least $65,000 (or $30,000 with at least $50,000 in deposits, investments, and insurance with HSBC).
- on Contactless & Online Spending for cardholders who maintain at least S$50,000 average daily balance in your HSBC EGA SGD Account
- S$1 = 20X Points (8 miles)
- on Contactless & Online Spending for all other cardholders
- S$1 = 10X Points (4 miles)
- on All Other Spend
- S$1 = 1X Point
Get Upsized S$430 Cash or 6,140 SmartPoints (use SmartPoints earned to redeem the latest Apple products on our Rewards Store) when you spend a min. of S$500 within 30 days from Card Account Opening Date!
Dive into spooktacular Halloween rewards with MoneySmart! Each day, the first 10 fastest claimants snatch exclusive Flash Deal prizes—from iPhone 18 Pro, MacBook Neo, Switch 2, PS5 and more—on top of your baseline reward! T&Cs apply.
7. DBS Woman’s Card (2 mpd, up to $1,000/month spend)
- Maximum earn rate: 2 mpd
- Bonus spend category: Online purchases
- Minimum spend: None
- Monthly spend cap: $1,000
The DBS Woman's Card is the entry-level sibling of the Woman's World Card. It has the same $1,000 monthly online cap and a much lower income requirement of $30,000, but half the earn rate at 2 mpd. And again, points are awarded only in $5 spending blocks.
- $5 online spend = 5 DBS Points (2 mpd)
- $5 other spend = 1 DBS Point (0.4 mpd)
So if you make a lot of small online purchases (under $5 each), this might not be the most efficient option. At 2 mpd, it's the lowest earner among the miles cards here. However, one draw is complimentary e-Commerce Protection on online purchases, which is handy for big-ticket buys that might not arrive as promised.
The $1,000 monthly cap on bonus points applies here, so plan your big buys accordingly. The annual fee is $163.50 after the first-year waiver, and DBS Points expire after 12 months.

- on Online Purchases
- S$5 = 5 DBS Points (2 Miles per S$1)
- on Other Purchases
- S$5 = 1 DBS Point (0.4 Miles per S$1)
- e-Commerce Protection for Online Purchases
- Complimentary
Cashback cards
8. Citi SMRT Card (up to 5% cashback, $12,000/year spend)
- Maximum cashback: 5%
- Bonus spend category: Online purchases (plus groceries, taxis, ride-hailing, and SimplyGo)
- Minimum spend: $500/month
- Spend cap: $12,000/year (equivalent to SMRT$600 cashback)
The Citi SMRT Card is a cashback card that quietly excels when it comes to big-ticket spending—thanks to one rare feature: an annual cashback cap. While most cashback cards limit you with tight monthly caps, the SMRT Card lets you earn up to SMRT$600 per year, which translates to $12,000 in eligible spending.
As long as you hit the $500 monthly minimum spend, you’ll get 5% cashback (SMRT$) on online purchases, groceries, and transport. But what makes this card especially handy for buying furniture or electronics is the flexibility to make a large purchase in a single month without missing out on cashback—something monthly-capped cards can’t offer.
Just be sure to buy online to qualify for the 5%, and you’ll enjoy the full value of the annual cap, whether you make one big purchase or spread it out over the year. Also note that once you hit the SMRT$600 cap, you won't earn any more cashback until it resets, so a $12,000 splurge would use up a whole year's worth.
One of my favourite things about the Citi SMRT card is its simplicity: SMRT$1 = $1 cashback, so tracking your rewards is straightforward.
 Medium.jpeg)
- on Online Purchases, Groceries, Taxi, Ride-hailing, SimplyGo & Malaysia Ringgit Spend
- 5% Savings
- on Other Retail Spend
- 0.3% Savings
- Min. Spend per statement month to earn max rebates
- S$500
Snap up baseline gifts: be among the first 200 approved applicants spending S$500 to enjoy S$450 Upsized Cash or a S$500 Amazon.sg Gift Card, or still grab S$400 Cash or 6,140 SmartPoints (use SmartPoints earned to redeem the latest Apple products on our Rewards Store) if you come after.
But the real treat? Dive into spooktacular Halloween rewards with MoneySmart! Each day, the first 10 fastest claimants snatch exclusive Flash Deal prizes—from iPhone 18 Pro, MacBook Neo, Switch 2, PS5 and more—on top of your baseline reward! T&Cs apply.
9. American Express True Cashback Card (up to 3% cashback, $5,000/month spend)
- Maximum cashback: 3% (on first $5,000 spend for new cardholders)
- Bonus spend category: None (flat rate cashback)
- Minimum spend: None
- Spend cap: $5,000 for 3% (first 6 months only); unlimited 1.5% cashback thereafter
The American Express True Cashback Card is one of the simplest and most fuss-free options if you’re planning to make a large purchase upfront—like furnishing a new home or upgrading electronics. New cardmembers enjoy 3% cashback on the first $5,000 spent within the first 6 months. That’s a potential cashback of $150 right out of the gate, with no category restrictions, no promo hoops, and no minimum spend required.
After the initial bonus period, you’ll continue to earn a flat 1.5% cashback on all eligible spend, with no monthly or annual cap. This makes it ideal for buyers who value predictability and flexibility, especially if you’re not the type to track merchant codes or optimise for bonus tiers.
The flat cashback structure means you're rewarded no matter what you buy—furniture, electronics, airfares, or groceries. Just swipe and earn. That said, check that your furniture or electronics store accepts American Express before you head to the checkout. Cashback shows up in the same month's statement, and the annual fee is $174.40 after the first-year waiver.
 (1).png)
- on all eligible purchases, up to S$5,000 spend in first 6 months for new Card Members
- 3.0% Cashback
- all subsequent eligible purchases
- 1.5% Cashback
- Cash Back Cap
- Unlimited
10. HSBC Advance Credit Card (up to 2.5% cashback, $2,800/month spend)
- Maximum cashback: 2.5%
- Bonus spend category: None (applies to all eligible spend)
- Minimum spend: >$2,000/month
- Monthly spend cap: $2,800 (cashback capped at $70/month)
If you're planning a big-ticket purchase and can consolidate your spending in a single month, the HSBC Advance Credit Card offers one of the highest general cashback rates available—up to 2.5% on all spend, local or overseas.
To qualify for the top rate, you'll need to spend more than $2,000 in a calendar month. Once you do, all your eligible spend up to $2,800 will earn 2.5% cashback. That nets you a maximum of $70 cashback per month. Anything beyond that earns no further cashback, so this card is best when you can strategically time a big purchase within the cap.
Outside of this tier, the card still gives you 1.5% base cashback with no minimum spend, so there’s value even on lower months. The $70 monthly cap still applies, though.
You'll need an annual income of at least $65,000 (or $30,000 with at least $50,000 in deposits, investments, and insurance with HSBC) to qualify, and the annual fee is $196.20 after the first-year waiver.
- Base Cashback
- 1.5%
- Cashback when you spend more than S$2,000
- 2.5%
- Cashback Cap per month
- S$70
Get S$400 Cash or 6,140 SmartPoints (use SmartPoints earned to redeem the latest Apple products on our Rewards Store) when you spend a min. of S$500 within 30 days from Card Account Opening Date!
Dive into spooktacular Halloween rewards with MoneySmart! Each day, the first 10 fastest claimants snatch exclusive Flash Deal prizes—from iPhone 18 Pro, MacBook Neo, Switch 2, PS5 and more—on top of your baseline reward! T&Cs apply.
11. DCS Ultimate Platinum MasterCard (up to 2% cashback, $10,000/month spend)
- Maximum cashback: 2%
- Bonus spend category: None (applies to all spend)
- Minimum spend: None
- Monthly spend cap: $10,000 (cashback capped at $200/month)
The DCS Ultimate Platinum MasterCard is a flat cashback card that quietly competes with the big players—offering 2% cashback on all spend with no minimum spend required.
You can earn up to $200 cashback each month, which effectively applies to the first $10,000 in monthly spend. That makes it a good fit if you're planning a large one-off purchase—like renovating a home or buying premium appliances—and don’t want to track category bonuses or minimum spends.
As a nice bonus, cardholders enjoy complimentary insurance coverage of up to $1 million, adding a layer of lifestyle protection to your spending.
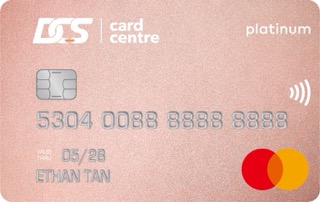
- Cashback on the first S$10,000 spent
- Earn 2%
- Min. Spend
- S$0
- Cash Back Cap per month
- S$200
12. Hate tracking MCCs? Try these unlimited cards instead
If you find yourself constantly asking “Wait, will this transaction qualify for bonus miles?” or struggling to keep up with monthly spend caps and eligible MCCs—you’re not alone.
Some of us just want a card that works every time, no mental gymnastics required. That’s where unlimited cashback and general-spend miles cards come in. These are your best bets if you want to earn rewards with zero effort, whether you’re a cashback fan or a miles chaser.
Unlimited cashback credit cards
These cards offer flat-rate cashback on local spend with no minimum spend and no caps. Simple mechanics, straight-up value.
Card | Cashback rate | Card association | Extra perks |
1.7% | American Express | Up to 2% on contactless spend until 31 Jan 2027 | |
1.6% | Mastercard | Cashback never expires and can be redeemed instantly | |
1.6% | Mastercard | Cashback auto-credited to your card account | |
1.5% local; 1.5% on overseas spend (first $1,500/month) | Mastercard | No foreign currency fee; 1.5 Shopee Coins per $1 on Shopee | |
1.5% | Mastercard | Dining and shopping privileges via The Good Life programme |
General-spend miles cards
Prefer to earn miles on everything you swipe, without worrying about category exclusions? These entry-level cards offer stronger base earn rates and, in some cases, bonuses on travel bookings.
Card | Local Spend | Overseas Spend | Bonus Spend |
1.4 mpd | 2.4 mpd (3 mpd in Indonesia, Malaysia, Thailand, and Vietnam) | Up to 8 mpd via UOB’s Agoda & Expedia booking portals | |
1.3 mpd | 2.1 mpd (foreign currency spend) | Up to 7 mpd on Agoda stays | |
1.3 mpd | 2.2 mpd (foreign currency spend) | DBS Points never expire |
No matter your reward preference—cashback or miles—these “limitless” options are ideal if you value simplicity, consistency, and flexibility. So if keeping tabs on merchant codes and bonus tiers feels like a full-time job, it might be time to make the switch.
Found this article useful? Share it with your family and friends!
Related Articles