What do the UOB Lady’s Card, Trust Freedom Card (on bonus cashback mode), and Maybank Family & Friends Card have in common? They all let you choose your own bonus category or categories. This sounds great in theory, but my issue with this mechanism has always been one of effort. To properly ascertain which category (or categories) you’ll earn the most rewards on, you’d have to carefully track your spending across all categories. Sure, you can wing it and say you pretty much always spend the most on dining… but what if you don’t?
Enter the new DBS Chromo Card. This card introduces an enhanced version of the “pick your best category” mechanism—it does the picking for you. And it does it better. Each month, it pays up to 5% cashback on the 2 categories you spent the most on, once you spend at least $500. It also lets you switch to earning 1.3 miles per dollar (mpd) instead, once a month. The catch? It’s only for 21 to 29-year-olds. So is it the best first credit card for your 20s?
[ms-toc title="DBS Chromo Card MoneySmart Review (2026)"]
DBS Chromo Card review—Is it MoneySmart?
See our credit card ranking rubric to find out how we rank credit cards.
1. DBS Chromo Card—Summary
.png)
- on your top 2 local spend categories every month
- Up to 5% Cashback
- & 5-year annual fee waiver
- 0 FX Fees
- Flexibility to choose your reward preference every month
- Miles or Cashback
The DBS Chromo Card is an everyday rewards card for young adults in Singapore, with 2 reward modes. By default, you’re on cashback mode, which pays up to 5% cashback on your top 2 spending categories. You can also switch to miles mode, which earns a flat 1.3 mpd on eligible local spend. For most people, cashback mode is the more rewarding of the two (we crunch the numbers in section 5), so that’s the focus of this review.
Here’s how the rates for both modes break down:
Since each category’s bonus cashback is capped at $30, the 5% rate effectively applies to the first $750 of spend in each of your top 2 categories. That’s up to $60 of bonus cashback a month. The $150 overall cap is unlikely to affect most people because you’d need about $9,000 of eligible spend in a month to reach it.
Cashback is automatic. You don’t need to register or redeem anything, and it’s posted to your card statement. Base cashback earned in a calendar month is credited within 30 days after the month ends. Bonus cashback takes a little longer: within 60 days after the month ends.
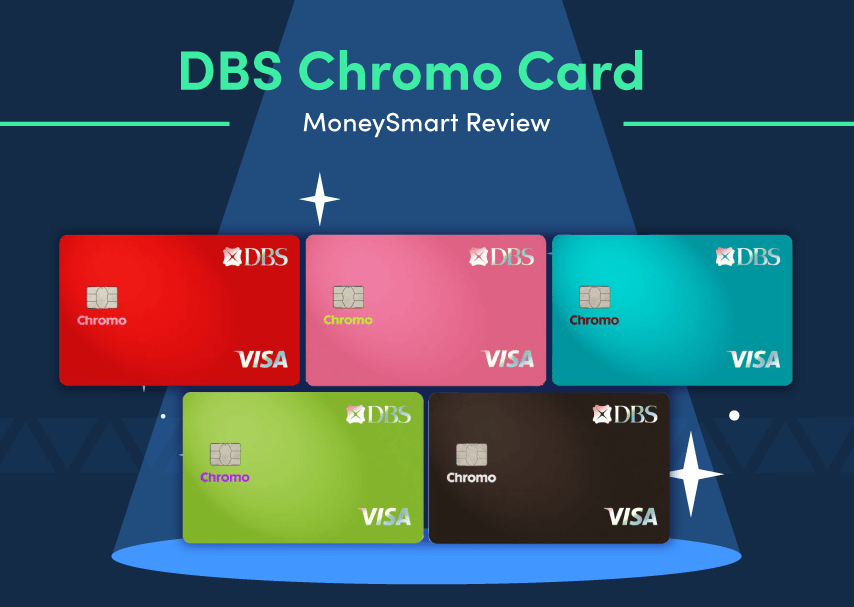
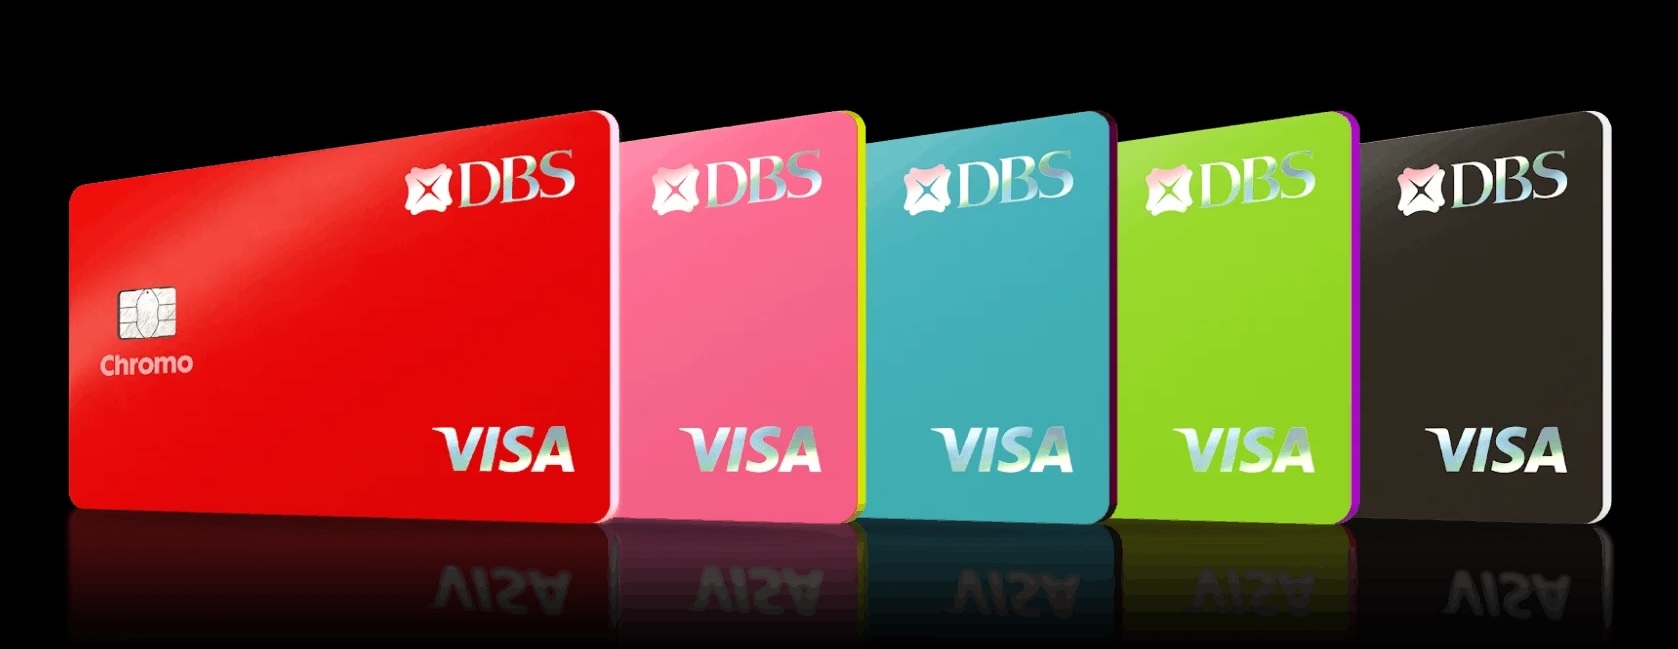
The card is also a Visa, which you can add to Apple Pay, Google Pay and Samsung Pay. You can pick from 5 card colours: Red, Pink, Teal, Lime and Charcoal.
2. How the DBS Chromo Card Works
The Chromo Card works on a calendar-month basis, not your statement cycle. That matters when you’re timing your spending. A purchase on 31 March counts towards March, even if it only shows up on your April statement. DBS calculates rewards based on the transaction date, as long as the transaction has been posted by the time rewards are computed.
Earning cashback on DBS Chromo
Here’s how DBS works out your cashback each month:
- Checks your minimum spend. Did you charge at least $500 of qualifying retail transactions to the card this month?
- Ranks your categories. DBS totals your eligible spend in each of the 6 Spend Categories and picks the top 2. If 2 or more categories are tied, DBS decides which ones qualify.
- Pays out. Your top 2 categories earn 5%. All other eligible local spend earns 1%.
If you don’t reach $500 in a month, everything earns the 1% base rate.
Switching between cashback and miles
Every Chromo cardholder starts on cashback by default. In the DBS digibank app, you can switch your Rewards Preference to miles. You’ll then earn 1.3 mpd on eligible local spend, with no cap and no minimum spend.
A few rules to know:
- You choose after the month ends. Whichever preference is active on the 10th of the following month applies to the previous month’s spend. For example, your preference on 10 May decides whether April’s spend earns cashback or miles.
- You can switch once per calendar month, and switches are final.
- A month’s spend can’t be split. It earns either cashback or miles, not both.
This is the card’s most interesting feature. By the 10th, you already know whether you hit $500 last month. If you did, cashback is usually the better deal. If you didn’t, 1.3 mpd may be worth more to you than 1% cashback. (See section 5 for the numbers!)
How DBS Chromo awards miles
Your miles don’t land in your account as miles. They come as DBS Points, and 1 DBS Point is worth 2 miles. For each transaction, DBS works out your points like this:
- Divide the transaction amount by $5.
- Multiply by 3.25 to get your DBS Points.
- Round down to the nearest whole point.
Why $5 and 3.25? It’s simply how DBS expresses 1.3 mpd in DBS Points. Every $5 you spend earns 3.25 DBS Points, which is 6.5 miles—and 6.5 miles divided by $5 is 1.3 mpd. Honestly, if this is confusing to you, no worries. Understanding the math is non-essential.
What is good to know is that there is rounding involved, and this is what trips people up. DBS only credits whole points, and it rounds each transaction separately, not your monthly total. Here’s what that looks like, using DBS’s own examples:
You lose less than 1 DBS Point (2 miles) per transaction to rounding. That’s negligible on a $500 flight, but it adds up across lots of small purchases like coffee and bubble tea. If you plan to use miles mode, bigger transactions get you closer to the full 1.3 mpd.
Converting DBS Points to miles
DBS Points earned on the Chromo Card don’t expire. You can convert them to these frequent flyer programmes:
Each conversion costs an administrative fee of $27.25. You can also redeem DBS Points for cash credits, shopping and dining vouchers, and other items in the DBS Rewards catalogue.
What happens when you turn 30
Interestingly, you can’t apply for the DBS Chromo Card once you’ve turned 30. So the only way to be 30 and above and have the card is if you already held the card in your 20s. Then, it stays active, and your current rewards continue for 3 months after your 30th birthday month. After that:
- Cashback mode: you earn a flat 1.7% cashback on eligible spend, with no cap and no minimum spend. Bonus cashback no longer applies.
- Miles mode: you continue earning 1.3 mpd.
For example, if your 30th birthday is on 30 January 2028, the change takes effect from 1 May 2028. The 0% foreign currency transaction fee and the monthly cashback/miles switch stay.
3. What counts as eligible spend?
To earn cashback or miles, a transaction must be local retail spend charged to the card. To earn bonus cashback, it must also be charged in Singapore dollars, in-store or online, and fall under one of these Spend Categories by its merchant category code (MCC):
The Wellness category deserves a closer look. Supermarket spend is included, so groceries can earn 5% in months when it’s one of your top 2. Gym memberships only count at these brands: Anytime Fitness, ClassPass, Virgin Active, Fitness First, Body Fit Training, True Fitness, 247 Fitness, Pure Yoga, Revl Training, True Yoga and Revolution SG.
Not sure how a merchant is coded? DBS decides based on the MCC the merchant’s bank assigns. You can check the MCC of any posted transaction through the DBS digibot on the DBS website. DBS explains how in FAQ 37 of the DBS Chromo Card FAQ.
For the full MCC lists, see the Terms and Conditions Governing the DBS Chromo Card.
Key exclusions to know
Foreign-currency transactions don’t earn rewards. The Chromo Card charges no foreign currency transaction fee, but spend charged in a foreign currency earns no cashback and no miles. This applies to both overseas and online spend. It still counts towards your $500 minimum spend.
Paying in SGD overseas (DCC) earns rewards, but check the rate. When an overseas merchant offers to charge you in Singapore dollars through dynamic currency conversion (DCC), the transaction does earn cashback or miles, and DBS waives its DCC fee. But the merchant’s DCC exchange rate is often worse than Visa’s rate, so compare before you agree. On a $100 purchase, a rate that’s 3% worse costs you about $3. That’s more than the 1% base cashback you’d earn, and most of a 5% bonus.
Some transactions earn nothing at all:
- Top-ups and payment platforms: EZ-Link top-ups, YouTrip, Amaze, ShopeePay, RazerPay, Singtel Dash, SmoovPay and similar
- Bill payments via AXS, SAM or internet banking
- Utilities (MCC 4900), even when charged directly to your card
- Insurance premiums, education fees, hospitals, tax and government services, fines, and charitable donations
- Rent (real estate agents and managers), parking, tolls, cleaning services and betting
- Instalment plans: 0% Interest Instalment Payment Plan and My Preferred Payment Plan monthly transactions
- Cash advances, balance transfers, interest and DBS fees
Some payment platforms don’t earn bonus cashback. Transactions through services like CardUp, iPaymy and Fave are excluded from the bonus Spend Categories, even if the underlying merchant would otherwise qualify.
4. Fees, charges, and card eligibility
Card fees and charges
Card eligibility
- Age: 21 to 29 years old at the time of application. If your 30th birthday is today, or has already passed, you can’t apply.
- Minimum annual income: $30,000 for Singaporeans and PRs, $45,000 for foreigners
- Secured card issuance isn’t available for the DBS Chromo Card.
5. Cashback calculation
Let’s see what the Chromo Card could earn you in a typical month. Say you’re 26, and your month looks like this:
You’ve cleared $500, and Dining and Shopping are your top 2 categories, so they earn 5%. Both stay well under the $30 bonus cap per category. Your total cashback is $30.80, an effective rate of 3.5%. If you had spent only $450 that month, everything would earn 1%, giving you just $4.50.
What happens in a travel month
Now say you book a holiday. You pay $1,200 for flights and a hotel in Singapore dollars, and spend $300 on dining:
Travel is your top category, but its bonus is capped at $30, which you reach at $750 of spend. The remaining $450 of travel spend earns only the 1% base. Your total is $57, an effective rate of 3.8%.
Spending overseas on the same trip? The Chromo Card charges no foreign currency transaction fees. Foreign-currency spend earns no cashback, but it does count towards your $500 minimum spend, so it can help unlock the bonus on your SGD bookings.
DBS Chromo Card—cashback or miles?
Take the $880 month from the first example. In cashback mode, you get $30.80. In miles mode, you’d get up to about 1,144 miles instead (slightly fewer after rounding). So how much are those miles worth? It depends on how you redeem them, but flight redemptions typically work out to about 1.5 to 2 cents per KrisFlyer mile. At a baseline of 1.5 cents, 1,144 miles is worth about $17—roughly half the $30.80 you’d get in cashback. Even at 2 cents, it’s only about $23. So in months when you hit $500, cashback is usually the better pick, unless you’re saving towards a specific award flight.
In a month where you miss $500, the maths flips. Every $100 you spend earns just $1 in cashback mode, but 130 miles in miles mode. At 1.5 cents a mile, those 130 miles are worth about $1.95—nearly double the cashback.
One more thing: DBS lists miles conversions at 5,000 DBS Points for 10,000 miles, which takes roughly $7,700 of eligible spend to earn in miles mode.
6. Is the DBS Chromo Card worth it?
For most people aged 21 to 29, yes—as long as you regularly spend at least $500 a month in Singapore.
Pros of the DBS Chromo Card
- No category management: your top 2 categories are picked for you each month.
- Broad bonus categories: including groceries, gyms, telco bills and streaming.
- 1% base rate: higher than the 0.2% to 0.3% on many category-based cashback cards.
- Cashback or miles: choose after each month ends.
- 0% FX and DCC fees, plus a 5-year annual fee waiver.
- Still useful after 30: a flat, uncapped 1.7% cashback.
Cons of the DBS Chromo Card
- Tight bonus caps: 5% only applies to the first $750 per category.
- No rewards on foreign-currency spend, despite the 0% FX fee.
- Only 2 categories earn the bonus: evenly spread spending mostly earns 1%.
- Age-limited: you must apply before 30, and bonus cashback ends after.
- Slow bonus payouts: up to 60 days after month end.
Checklist: Is the DBS Chromo Card for you?
- Are you aged 21 to 29?
- Do you spend at least $500 a month on your credit card?
- Is most of your spending local and in Singapore dollars?
- Do 1 or 2 categories—like dining, shopping or groceries—usually account for much of your spending?
- Would you like the option to earn miles in some months?
If you answered yes to most of these, the DBS Chromo Card is a strong, low-effort pick for your wallet.
7. DBS Chromo Card promotion
New to DBS/POSB credit cards? You can pick either:
- A Samsonite MINTER 80/30 Trunk Luggage (worth $680) with promo code CMSAM, or
- $288 cashback with promo code CM288
To qualify:
- You must not currently hold a principal DBS/POSB credit card, and must not have cancelled one in the last 12 months.
- Apply for the DBS Chromo Card between 5 September 2026 and 31 October 2026, and enter your chosen promo code in your application.
- Have your card approved by 14 November 2026.
- Spend at least $500 within 60 days of card approval.
- Have a valid DBS PayLah! account by the end of those 60 days.
How you’ll receive your gift:
- $288 cashback: credited to your card account within 3 to 5 months of meeting the minimum spend.
- Samsonite luggage: DBS will mail you a Reward Notification letter within 3 to 6 months of meeting the minimum spend. Bring the original letter to the designated redemption centre before the stated redemption deadline, or you forfeit the gift.
- The luggage comes in Cherry Blossom, Glossy Sage Green or Black, while stocks last. Colours are first come, first served and can’t be reserved.
- It comes with a 3-year Samsonite warranty.
- If the luggage runs out, DBS may give you $288 cashback instead.
T&Cs apply.
- on your top 2 local spend categories every month
- Up to 5% Cashback
- & 5-year annual fee waiver
- 0 FX Fees
- Flexibility to choose your reward preference every month
- Miles or Cashback
8. Alternatives to consider
If the Chromo Card’s age limit, caps or foreign-currency exclusion don’t suit you, here’s how it compares with 3 alternatives:
Best for overseas spenders and 30-somethings: Maybank XL Cashback Card
The Maybank XL Cashback Card is the Chromo Card’s closest competitor. It earns 5% cashback on Dine, Shop, Travel and Play spend, plus foreign-currency spend overseas and online, once you spend at least $500 in a calendar month. Cashback is capped at $80 a month, and other spend earns 0.2%. It also has a wider age window: Maybank only accepts applicants aged 21 to 39.
It’s a better fit if you often spend in foreign currencies, where the Chromo Card earns nothing. The trade-off is that Maybank charges a 3.25% fee on all overseas spending, which eats into your 5%. Its annual fee is $87.20, waived for the first 2 years.
 Medium.jpeg)
- on Dine, Shop, Travel and Play categories
- 5% Cashback
- on Foreign Currency Spend
- 5% Cashback
- Min Spend per month
- S$500
Best for online and tap-to-pay spenders: UOB EVOL Card
The UOB EVOL Card suits people who shop online and pay by phone. It pays 10% cashback on selected gym, telco and streaming spend, local online spend and mobile contactless spend when you spend at least $800 per statement month. Cashback is capped at $80 a month: $20 for gym, telco and streaming, $30 for local online and mobile contactless, and $30 for all other spend.
Those per-category caps are tighter than the Chromo Card’s. At 10%, you max out the online and mobile contactless cap after just $300 of spend, and the gym, telco and streaming cap after $200—well short of the $800 minimum spend. So to get the most out of the UOB EVOL, you have to spread your spending across several categories. The Chromo Card has category caps too, but you only reach its $30 bonus cap at $750 of spend, which is more than its $500 minimum spend. That means you can use it as a 1-category card—putting all $500 on dining, say, and earning 5% on the lot—which makes its caps much easier to live with.
Like the Chromo Card, it has no FX fees. Unlike the Chromo Card, you currently earn cashback overseas too: 0.5% on FX spend in China and Europe, and 1% on other overseas FX spend, until 31 December 2026. UOB also says annual fees are waived from 1 July 2026, with no minimum spend required.

- on Local Online, Mobile Contactless, Telco, Gym, Streaming spend
- 10% Cashback
- FX Fees on overseas FX spend worldwide, with no min spend, no cap
- 0%
- Min. Spend per month for 10% cashback
- S$800
Best if you can’t hit $500 every month: Citi Cash Back+ Card
If your spending varies a lot, or you’d rather not track categories and caps, the Citi Cash Back+ Card is the simple option. You earn 1.6% cashback on all eligible spend, with no minimum spend and no cap, and cashback doesn’t expire. You’ll earn less than the Chromo Card in months when you hit $500. But in lighter months, 1.6% beats the Chromo Card’s 1%, and there’s no age limit.
What about after you turn 30? The Chromo Card’s flat 1.7% (see section 2) is slightly more than the Citi Cash Back+ Card’s 1.6%, so there’s no need to switch cards at 30.

- Cash Back on Eligible Spend
- 1.6%
- Min. Spend per month
- S$0
- Cash Back Cap per month
- Unlimited
Get S$400 Cash Reward or 6,140 SmartPoints (worth up to S$649 of Gifts) as quickly as 5 weeks —just spend S$500 within 30 days of card approval with your new Citibank Credit Card! T&Cs apply.
9. Final words
So, is the DBS Chromo Card the best first credit card for your 20s? For a lot of young adults, it’s a strong contender. It takes the effort out of the “choose your own category” model: your top 2 categories earn 5% automatically, all other local spend earns 1%, and you can switch to miles when that makes more sense. If you spend at least $500 a month and mostly in Singapore dollars, it’s an easy card to recommend. If you spend heavily overseas, regularly go beyond $750 in a single category, or turn 30 soon, one of the alternatives above may suit you better.
P.S. Here’s our MoneySmart credit card ranking rubric
In case you’re wondering, here’s how we decide on our credit card rankings.
Found this article useful? Share it with your family and friends!
Related Articles