If you feel like you're on the Grab app constantly, you're not alone. In fact, far from it. Grab hit a whopping 52 million monthly active users in the first quarter of 2026, a 24% jump from the year before.
In 2026, you’d be hard-pressed to find a Singaporean who isn’t familiar with Grab. After all, for many Singaporeans, Grab isn't just an app you open when you're running late or too lazy to cook. It’s the go-to app for rides to work, food delivery or a nice meal out on a rough day, a top-up grocery run via GrabMart, the occasional Grab Dine Out booking, even parcels through GrabExpress.
What not everyone realises is that all these Grab expenses add up fast. When it comes to maximising your monthly expenditure, Grab spending can be a key category to earn cashback on. Yup, not “dining”, or “transport” as categories in isolation, but overall Grab spend.
The next question you might ask is this: how? What’s the best way to earn rewards on Grab? Enter the GXS Credit Card. Launched in August 2026, this card is arguably the first one built specifically around how Singaporeans actually use Grab and beyond. Instead of treating Grab as a bonus category buried under fine print, it puts Grab spending front and centre, with tiered instant unlimited cashback that scales with how much you actually use the app. Here’s why it’s the best cashback credit card for Grab spending in Singapore.
Key takeaways |
|---|
|
[ms-toc title="The Best Cashback Credit Card for Singaporeans Who Grab Everything"]
Why your Grab spending deserves its own cashback strategy
It's easy to mentally file Grab spending under "occasional treat"—a ride when it's raining, a food delivery order when you can't be bothered to cook. But for most people, that "occasional" spend is actually a real, recurring line in the monthly budget, right up there with groceries and transport.
The problem is that most cashback cards don't see it that way. Grab spending either gets excluded entirely from rewards, buried under a low monthly or quarterly cap, or gatekept behind a high minimum spend. If you're one of the many Singaporeans who taps Grab multiple times a week, that's significant cashback slipping through the cracks.
The GXS Credit Card fills that gap by building its rewards structure around Grab from the ground up. Here's exactly how that plays out.
How GXS Credit Card's Grab cashback tiers work
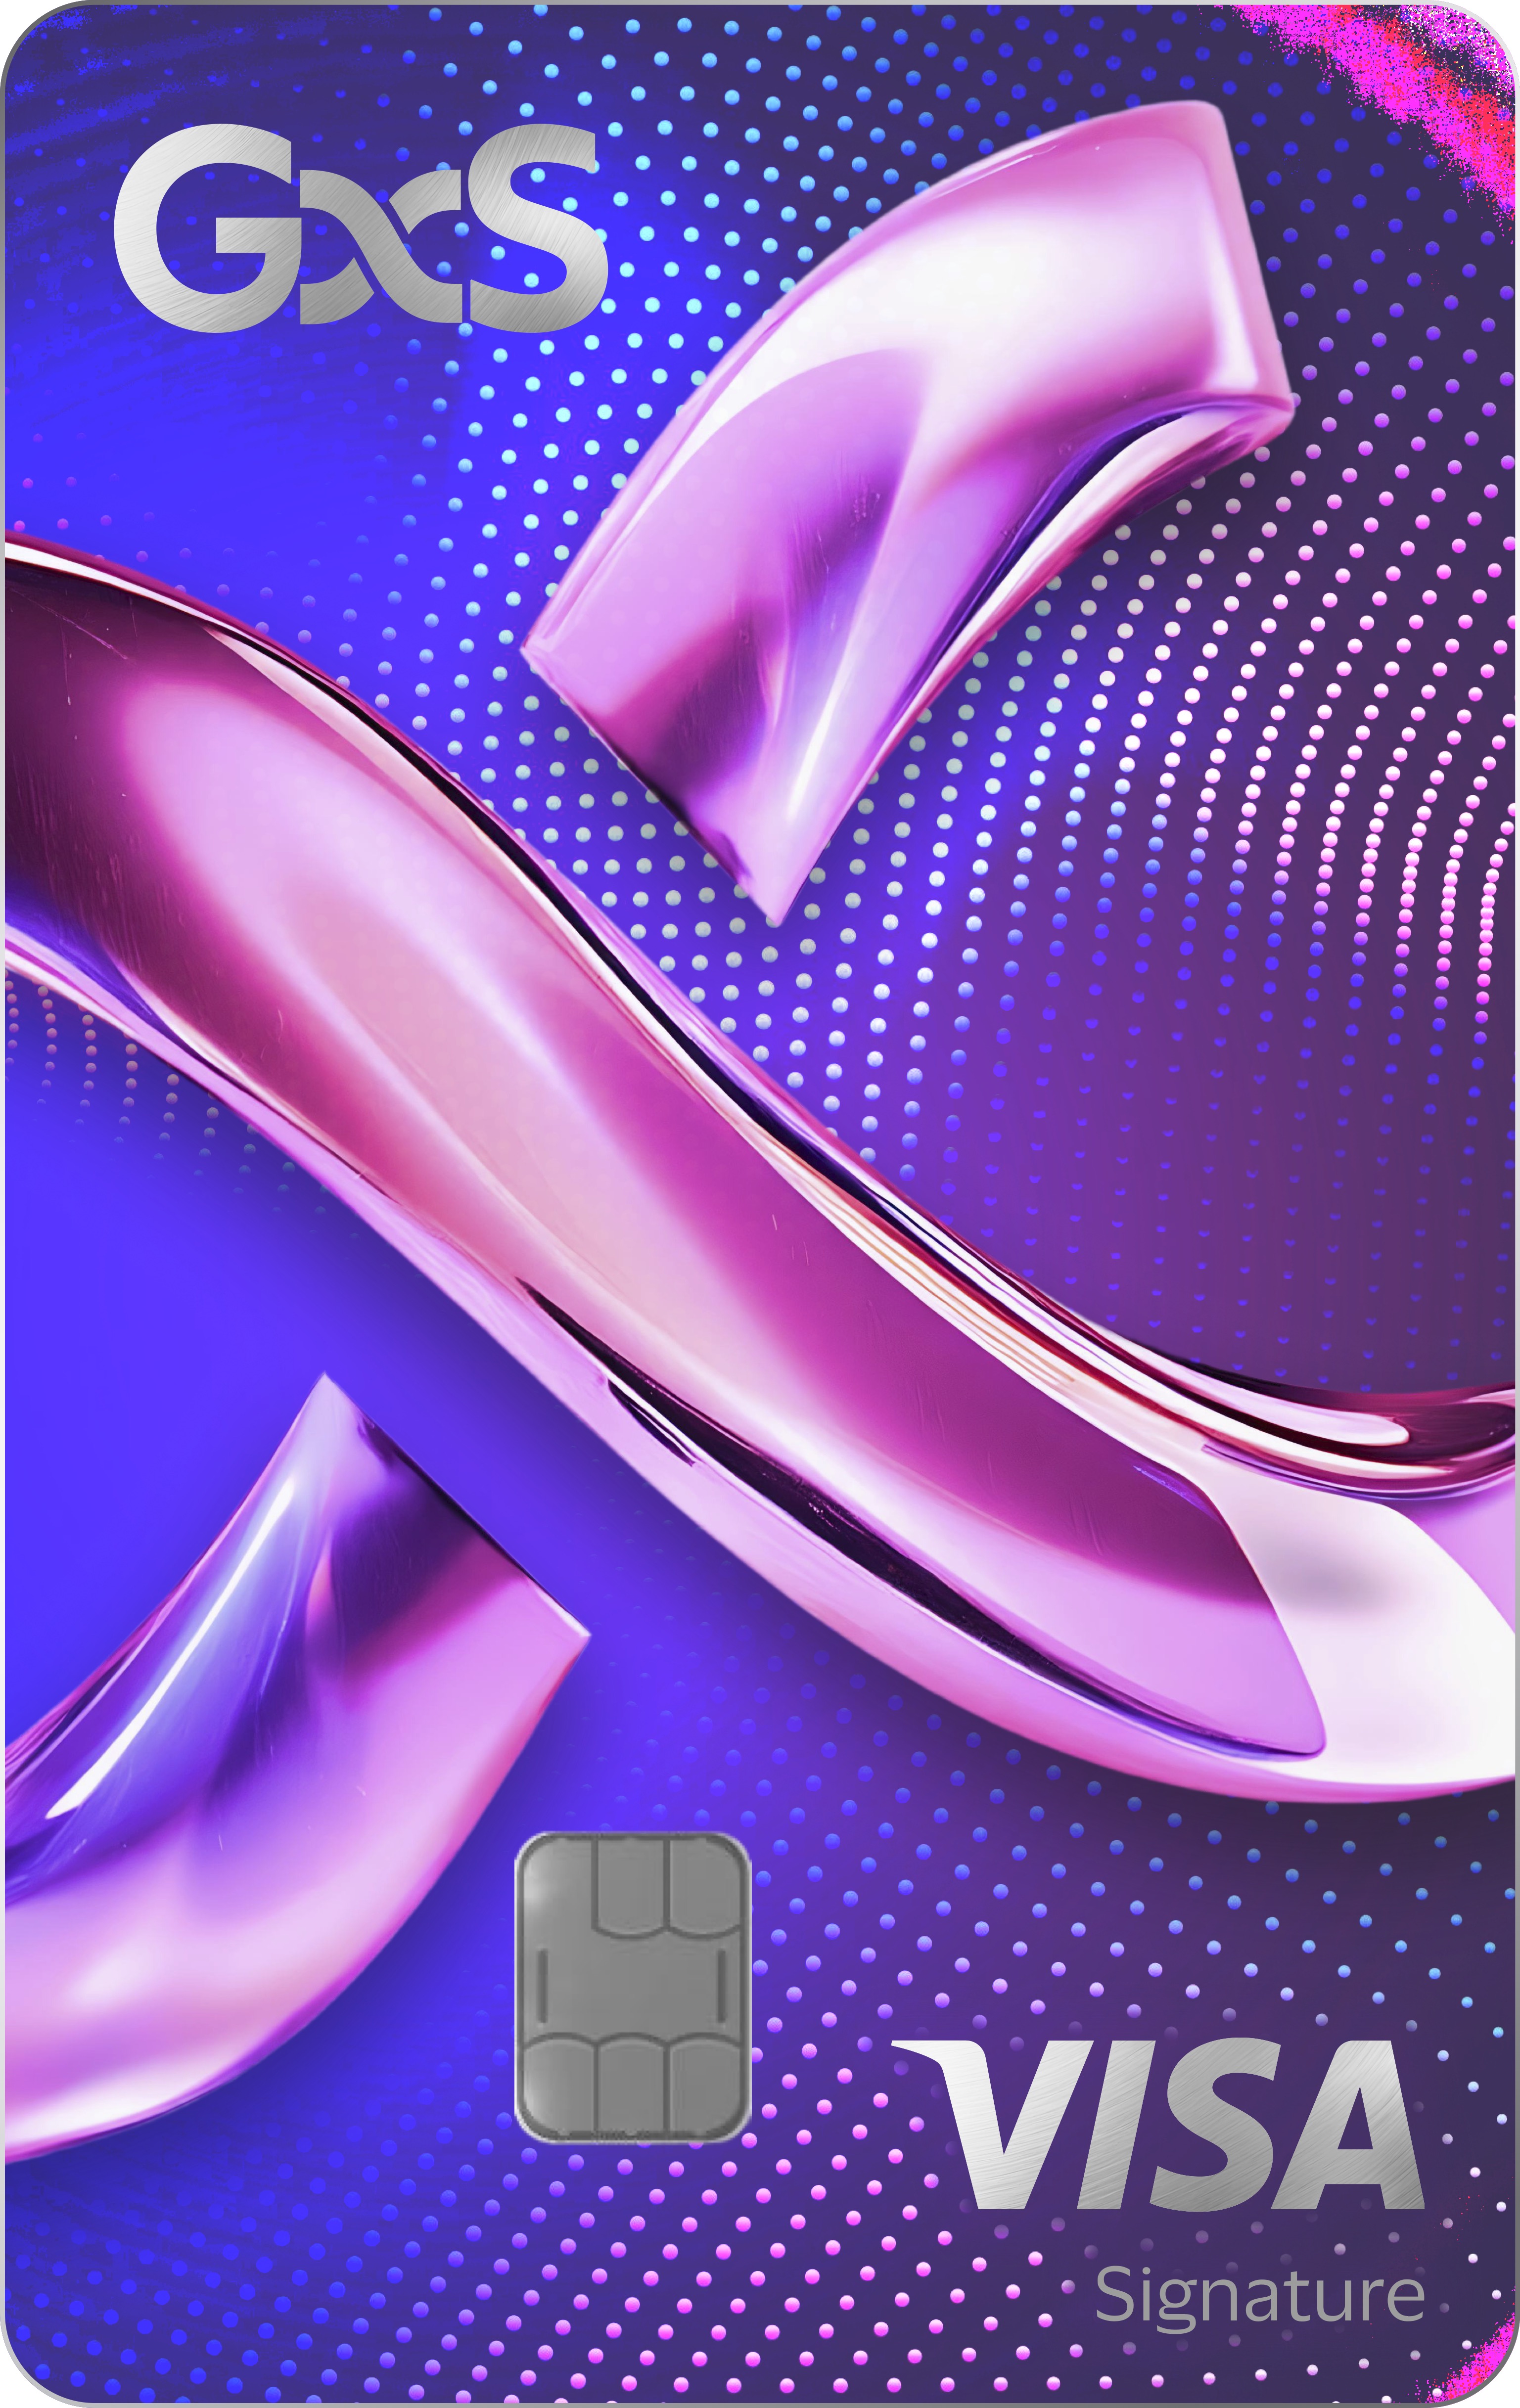
Image: GXS
So, how does the GXS Credit Card earn cashback on Grab spending? It offers instant unlimited cashback on Grab rides, GrabFood, GrabMart, GrabExpress, and Grab Dine Out. Your cashback is credited as GrabCoins right after each eligible transaction—no waiting for a quarterly statement cycle, no manual claims.
The rate scales in 3 tiers based on your monthly Grab spend:
- 3% instant cashback on all Grab spends with no minimum transaction size or spend required.
- 5% instant cashback on Grab spend that falls between $500 and $999.99 a month, once you've also spent at least $500 on non-Grab transactions.
- 10% instant cashback on Grab spend above $1,000 a month, with the same $500 non-Grab spend condition.
Here’s a summary of all the cashback categories and rates that the GXS Credit Card offers:
T&Cs apply. Cashback on Grab spending is credited instantly in GrabCoins after each transaction. Common exclusions apply across both card types, including insurance premiums, government payments, and education fees. Always check your card's eligible spend list for a full picture of what earns cashback.
You may have noticed all tiers come with unlimited transactions and no cashback cap. That means if you're a genuinely heavy Grab user, your cashback keeps climbing instead of flatlining once you hit some arbitrary ceiling. Even outside of Grab, at 1.75% with no earning cap, the GXS Credit Card offers the highest unlimited cashback rate with no cap for everyday local spending in Singapore.
Next, let’s take a look at what that looks like for a typical Grab spender.
A day in the life of a Grab-everything spender
Let's say your typical month looks something like this: a $15 GrabFood order most weeknights, a couple of Grab rides a week, a Grab Dine Out booking or two, a GrabMart grocery top-up, and the odd GrabExpress parcel. Add it up, and it's not unusual to hit $300–$400 in Grab spend a month without really trying.
At that level, you're sitting comfortably in the 3% tier, earning cashback on every single local Grab transaction with no minimum spend required to unlock it.
Push your Grab spend past $500 (say you added a longer airport ride or a bigger grocery haul), and as long as you've also spent $500 elsewhere on the card, any spend amount from $500 onwards jumps into the 5% tier.
The heaviest Grab users who are ordering GrabFood most days and taking multiple rides a week can find themselves comfortably in the 10% tier. Assuming they’ve also spent $500 elsewhere, any spend that is $1,000 and above earns them 10% uncapped cashback.
And if you're travelling, overseas Grab spend earns a flat 10% instant cashback regardless of which local tier you're in—no foreign transaction fees, no minimum spend. That $60 worth of overseas GrabCar and GrabFood spending in the table above already banks $6 in cashback on its own.
It's not just Grab—the rest of your spend earns too
The GXS Credit Card’s rewards don't stop at Grab. As long as you hit $500 in total monthly expenditure, all other eligible local spend earns a flat 1.75% unlimited cashback*. Eligible spend includes a wide range of categories—anything from your online shopping to fuelling up your car, or from food for your fur kid to catching a movie in a local cinema.
At 1.75% with no earning cap, the GXS Credit Card offers the highest unlimited cashback for most categories compared to other unlimited cards in Singapore.
Singtel bill payments earn 1.75% cashback too, with no minimum spend and no cap—so if you're already a Singtel customer, that's cashback on a bill you were paying anyway.
Put it all together, and you've got what's arguably the easiest cashback credit card for everyday spending in Singapore right now—one card, one flat rate for most of your local spend, tiered Grab rewards on top, and no categories to memorise.
The bottom line
If Grab is already part of your daily routine, the GXS Credit Card is built to reward exactly that kind of spending without asking you to jump through hoops to get there. Add in the highest unlimited cashback on everything else and Singtel bills, and you've got a card that's hard to argue with if you're already living the Grab-everything lifestyle.
From 25 September to 31 October 2026, new sign-ups can enjoy $108 off Grab rides, GrabFood, and GrabMart when you apply for the GXS Credit Card on the GXS Bank app today.
T&Cs apply.
Found this article useful? Share it with your fellow Grab-app addicts.
This post was written in collaboration with GXS. While we are financially compensated by them, we nonetheless strive to maintain our editorial integrity and review products with the same objective lens. We are committed to providing the best information in order for you to make personal financial decisions with confidence.
Related Articles