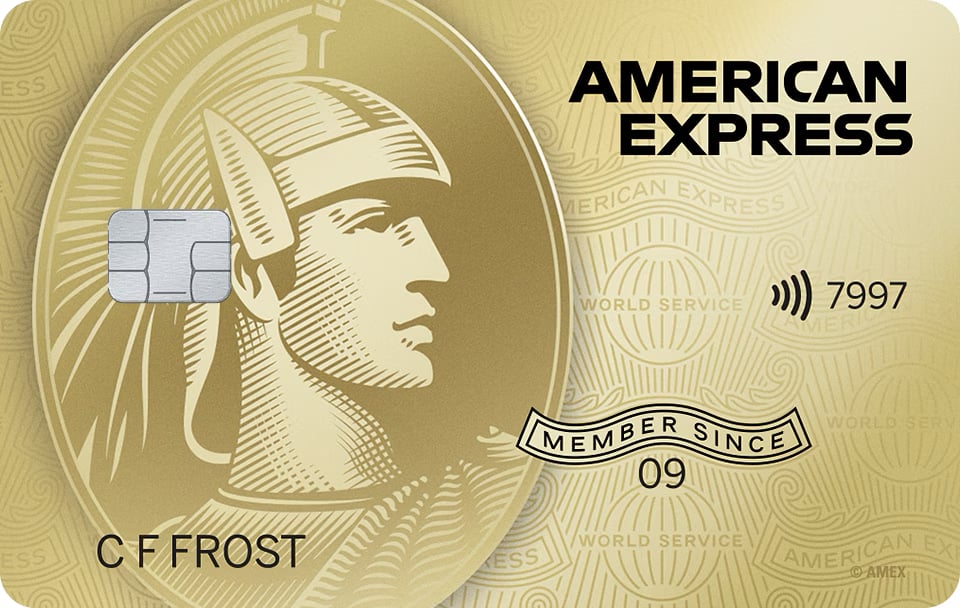
Looking for a fuss-free credit card that rewards you for every single purchase? The American Express True Cashback Card might just be your perfect match, offering a straightforward 1.5% cashback on everything you buy—without any monthly caps or complicated terms.
However, in a market flooded with flashy cashback cards promising the moon and stars, does this no-frills approach actually deliver? We've done the work to help you decide if Amex True Cashback Card deserves a spot in your wallet.
American Express True Cashback Card—Is it MoneySmart? | |||||
| |||||
Pros—What we like | Cons—What we don’t like | ||||
|
| ||||
Standard Chartered Smart Credit Card at a glance | |||||
Category | Our rating | The deets | |||
Earn rates: Cashback | ★★★☆☆ |
| |||
Earn categories | ★★★★★ |
| |||
Annual fees and charges | ★★★★☆ |
| |||
Accessibility | ★★★☆☆ |
| |||
Extras/periphery rewards | ★★★☆☆ |
| |||
Sign-up bonus | ★★☆☆☆ |
| |||
See our credit card ranking rubric to find out how we rank credit cards.
[ms-toc title="American Express True Cashback Credit Card Review (2026)"]
1. American Express True Cashback Card: How the cashback works
 (1).png)
- on all eligible purchases, up to S$5,000 spend in first 6 months for new Card Members
- 3.0% Cashback
- all subsequent eligible purchases
- 1.5% Cashback
- Cash Back Cap
- Unlimited
At first glance, the cashback rate of 1.5% isn't that impressive, especially when compared to other cards in the market. For better cashback, you can consider DBS Live Fresh Card with up to 6% cashback, the HSBC Live+ Card with up to 8% cashback, or the OCBC FRANK Card with up to 10% cashback.
However, upon closer inspection, cards that offer very high cashback rates usually only do so subject to 2 conditions: spending in certain categories, and that you satisfy their minimum spending requirements. This means a certain card might limit their generous cashback rate to specific categories (e.g. online purchases only), and/or require you to spend at least $600 a month to qualify for the cashback.
Therein lies the American Express True Cashback Card’s real strength—their 1.5% cashback rate is offered with no strings attached. Whether you're spending $50 on lunch at a restaurant, or dropping $5,000 on a new iMac at the Apple Store, you'll earn cashback—no questions asked.
Here's how the cashback works when buying home appliances at Harvey Norman:
First 6 months (3% cashback):
- Spend $3,000 on a new TV and fridge
- Cashback earned = $3,000 × 3% = $90
After 6 months (1.5% cashback):
- Spend $3,000 on home appliances
- Cashback earned = $3,000 × 1.5% = $45
Remember: The 3% cashback in your first 6 months is capped at $5,000 spend (maximum $150 cashback). After that, or if you exceed $5,000, everything earns 1.5% cashback with no cap.
What won't earn you cashback
Despite its generous earning structure, quite a number of transactions won't qualify for cashback:
Payment and Financial Transactions:
- Cash advances and other cash services
- Express cash withdrawals
- Balance transfers and instalment plans
- Late payment and collection charges
- Finance charges (including Line of Credit charges and credit card interest)
- Annual card fees
- Dishonoured cheque charges
Travel-Related:
- American Express Travellers Cheque purchases
- Tax refunds from overseas purchases
Digital Wallet:
- GrabPay top-ups (effective from 4 April 2023)
Other Exclusions:
- Charges processed before your card enrolment date
- Any prepaid charges before your first billing statement
- Transactions at merchants that American Express excludes from time to time
In fact, if any of these transactions are reversed or refunded, American Express will also deduct the cashback from your account at the same rate you earned them. Keep this in mind when planning your spending to maximise your rewards.
2. American Express True Cashback Card fees
Most of the fees that come with the Amex True Cashback Card are pretty standard. Here's a look:
American Express True Cashback Card | |
Annual fee & waiver | $174.40 (incl. of 9% GST) (waived for 1 year) |
Supplementary annual fee | Free for first 2 supplementary cards, subsequently S$87.20 (incl. of 9% GST) |
Interest free period | 22 days |
Annual interest rate | 27.80% |
Late payment fee | $100 if minimum monthly payment is not made by due date |
Minimum monthly repayment | 3% or $50, whichever is higher |
Foreign currency transaction fee | 3.25% |
Cash advance transaction fee | 5% per withdrawal |
Overlimit fee | – |
Card association | American Express |
Wireless payment | Apple Pay, Samsung Pay, Google Pay |
Notably, Amex will let you have 2 supplementary cards for free.
3. American Express True Cashback Card: Who should use it?
If you're planning some serious spending or gearing up for life's big moments, the Amex True Cashback Card could be your perfect match. Why? While most unlimited cashback cards falter under large transactions, the Amex True Cashback Card maintains its 1.5% earning rate whether you're dropping $50,000 on a wedding banquet or renovating your new home.
Just note that certain transactions won't earn you cashback (see full list here).
Strategic timing makes all the difference with this card, especially during your first six months when purchases earn 3% cashback up to $5,000. Time your big-ticket expenses right, and the returns practically write themselves.
What makes this card stand out is how it handles life's big-ticket expenses. From a destination wedding to that new home entertainment system, or even splurging on luxury bags - this card keeps the cashback flowing. While other category-specific cards restrict their rewards to certain spending types, Amex True Cashback card rewards every eligible purchase equally, making it your go-to card for significant expenses.
Where the card truly shines:
- Big electronic purchase, appliances, and furnishing
- Travel bookings and overseas spending
- Regular expenses across all categories
- Large purchases that exceed typical credit card caps
- Immediate cashback on the monthly statements
The card also comes with practical benefits like True Love Wedding privileges and home improvement deals, though these should be viewed as supplements rather than deciding factors.
Pro tip: If you're planning significant purchases, the first 6 months' enhanced rate effectively gives you an extra 1.5% discount on up to $5,000 worth of spending. After that, the consistent 1.5% rate continues without caps or conditions.
3. American Express True Cashback Card: How does it stack up against other cashback cards?
Let’s look at some similar cards on the market to see if they're a more suitable alternative to the American Express True Cashback Card.
GXS Credit Card–Best for Grab and Singtel loyalists
Unlike the flat-rate cards above, the new GXS Credit Card splits its rewards across 3 separate mechanics: 1.75% unlimited cashback on general retail spend, 1.75% cashback on Singtel bills, and bracketed GrabCoins on Grab spend that scale from 3% up to 10% depending on how much you spend that month. Overseas Grab spend skips the brackets entirely and earns a flat 10% GrabCoins, paired with zero foreign transaction fees.
What's better:
- 1.75% unlimited cashback beats Amex True Cashback Card's base amount
- Zero foreign transaction fees, plus that flat 10% GrabCoins rate on Grab spend made overseas
- All cashback categories on the GXS Credit Card are unlimited
What's not:
- The 1.75% base cashback only kicks in once you clear $500 in off-Grab spend that month
- Local Grab rewards are bracketed (3%/5%/10%), so your effective rate usually lands well below the 10% headline unless you're spending well past $1,000 on Grab a month
- GrabCoins land in your Grab account, not your card—they can't be converted to cash or transferred out
Smart take: Go for this card if you're already deep in the Grab and Singtel ecosystem and can comfortably clear the $500-a-month off-Grab minimum. If your spending doesn't naturally hit that threshold, or you'd rather not track brackets and minimums at all, Amex's uncapped 1.5% with zero conditions is the simpler bet.
Citi Cash Back+ Card–Earn cashback on rent and insurance with Citi PayAll

- Cash Back on Eligible Spend
- 1.6%
- Min. Spend per month
- S$0
- Cash Back Cap per month
- Unlimited
Get UPSIZED S$420 Cash Reward or 6,140 SmartPoints (worth up to S$649 of Gifts) as quickly as 5 weeks —just spend S$500 within 30 days of card approval with your new Citibank Credit Card!
PLUS get an additional S$50 Cash Bonus on top of your baseline gift if you are the first 15 claims at 9pm! T&Cs apply.
Moving up the cashback ladder, the Citi Cash Back+ offers a slightly higher base 1.6% unlimited cashback with no minimum spend requirement. For new cardmembers, there's a sweet cash reward via PayNow when you spend $500 in the first month.
What's better:
- Marginally higher base cashback (1.6% vs 1.5%)
- No minimum spend requirement
- Citi PayAll lets you earn cashback on rent, insurance, education fees, and other big-ticket payments
What's not:
- Lacks the 3% introductory cashback rate
- Dining discounts limited to selected restaurants
- Lower overall cashback for large purchases in first 6 months
Smart take: Choose this card if you're looking to earn cashback on recurring big-ticket payments through Citi PayAll, or if you prefer an immediate cash bonus over long-term higher rates. Perfect for those who value flexibility in payment options over higher introductory rates.
UOB Absolute Cashback Card–upsized 2% limitless bonus cashback till Jan 2027

- Cash Back on Eligible Spend
- 1.7%
- Min. Spend per month
- S$0
- Cash Back Cap
- Unlimited
Offering a competitive 1.7% unlimited cashback with no minimum spend, the UOB Absolute is already a heavyweight among the unlimited cashback cards in Singapore. But from now till 31 January 2027, UOB has made the deal even sweeter: enjoy up to 2% limitless bonus cashback on contactless spend till 31 January 2027.
What's better:
- Higher base cashback rate (1.7% vs 1.5%)
- Higher limited-time bonus cashback of 2% on eligible contactless spend
- Up to 15% fuel savings at SPC and 14% at Shell
- 1.7% cashback on entertainment subscriptions (Netflix, Disney+)
- Earns 0.3% on typically excluded spending (Grab top-ups, school fees)
What's not:
- Lacks the 3% introductory cashback offer
- Sign-up rewards require higher spending tiers
- Lower cashback on spend for excluded categories (0.3% vs 1.5%)
Smart take: Use this card after maximising your Amex True Cashback's 3% intro rate on the first $5,000. You'll effectively create your own two-card strategy—Amex for the first 6 months, then UOB for the long haul.
The Amex True Cashback Card isn't trying to be the highest-earning card in your wallet. Instead, it offers something rarer in Singapore's credit card scene: predictable rewards whether you're buying lunch or a laptop. Unlike cards that make you track categories and spending tiers, this one keeps it simple—just spend and earn, no complex calculations needed.
Found this article helpful for choosing between cashback cards? Share this article with your friends and family!
P.S. Here’s our MoneySmart credit card ranking rubric
In case you’re wondering, here’s how we decide on our credit card rankings.
Is that credit card MoneySmart? Our MoneySmart credit card ranking rubric | |
Category | Our rating |
Overall | The average rating for the credit card on the whole, calculated from the ratings for the individual categories below. Plus, we’ll give you a one-liner on who we think the credit card is best suited for. |
Earn rates: Air miles / Cashback / Rewards points | Air miles ✈️✈️✈️✈️✈️ / Cashback / Rewards points . This category looks at the depth rather than breadth of earn rates.
|
Earn categories | This category looks at the breadth rather than depth of your earnings.
|
Annual fees and charges |
|
Accessibility | Minimum income requirements:
|
Extras/periphery rewards | These include:
|
Sign-up bonus |
|
Related Articles