When was the last time you took a day off that was truly for yourself?
For many Singaporeans in their 40s and 50s, free time often comes second to family. Between caring for ageing parents and supporting children who may not be financially independent yet, there’s always someone who needs something. Welcome to the sandwich generation.
Sabrina (not her real name*), 52, knows this all too well. Her days off often mean accompanying her 70-year-old mother to medical reviews or taking her 80-year-old wheelchair-bound father-in-law for monthly check-ups. On top of that, she still helps out her 25-year-old son with his food expenses and insurance.
When so much of Sabrina’s time and energy goes into caring for her loved ones, it’s easy to put her own retirement plans on the back burner. But watching her parents’ health needs grow has her thinking, retirement won't wait for life to slow down. What are her retirement goals? How much will she need? Will her CPF savings be enough?
We worked through her projected retirement expenses, estimated what her CPF could provide, and explored how she could bridge any shortfall.
You’ve got everyone covered. Who’s looking after you?
It’s the unexpected expenses that can derail even the best budgeting plans: a medical bill, a loved one who needs caregiving, or a household appliance that suddenly breaks down.
As Sabrina puts it, “Some unexpected expenses may only be a few hundred dollars, but medical, dental, home repair or any family-related expenses can easily add up to a few thousand.”
Costs like these land on top of everything else she’s already juggling: mortgage repayments, family expenses and her own savings. “I would help my family as much as I can, but I also need to save for my own retirement,” Sabrina shared. That means trade-offs, like spending less on non-essentials so her savings come first.
Having seen how health challenges have stretched her family’s finances, time, and energy, she wants to plan ahead so her son won’t carry the same weight.
With retirement just five to ten years away, Sabrina started planning ahead for a future where her son won’t have to shoulder the same financial responsibilities she does. She began by asking herself:
- What kind of retirement do I want?
- How much will I need to fund it?
Define your retirement before you do the math
Most people start by looking at how much they have in the bank. While it’s a good start, that number means little until you know what you want your money to go towards. It can be daunting to juggle tons of research and possibilities on your own. If you’re not a numbers person, you may be dreading taking the first step.
Thankfully, retirement planning has become much more intuitive today. With the CPF Retirement Payout Planner, you can plan in bite-sized steps and get personalised suggestions on how to reach your retirement goal.
First, let’s start by imagining what your retirement could actually look like.
How do you envision your life in retirement?
Contrary to popular belief, retirement may not mean stopping work altogether. Some of us may prefer to work part-time, or explore meaningful projects; others may prefer to devote more time to self-care. Each decision comes with financial implications and affects how much you’ll need to save.
“I may still choose to work, but maybe something less stressful or less demanding. I also want to have more time for myself while I am still healthy enough to enjoy it,” she said, adding that she hopes to have more flexibility by her late 50s.
Travel with her husband is still on the cards. But she’s keeping things simple, with the occasional getaway rather than mandating two overseas holidays a year. “I don’t need a luxurious lifestyle.”
What matters most to her is having enough for daily expenses and healthcare, with some room for travel.
To see if her savings could support that, she started mapping out what she actually spends today:
Of course, not all of these expenses will follow her into retirement. Once her home loan is fully repaid at 60, that S$1,200 falls away, bringing her monthly expenditure down to S$3,500.
If you’re not sure where to start, the Retirement Payout Planner’s retirement payout guide can help estimate your monthly needs. Simply enter what you expect to spend on housing, food, transport, healthcare, and leisure, and it’ll calculate how much you may need each month to fund your preferred retirement lifestyle. No need to crunch the numbers yourself.
Will your CPF savings be enough?
The numbers were starting to take shape, but Sabrina still had one pressing question: how much monthly income could her CPF savings actually give her, and would it be enough for the retirement she hoped to enjoy?
Putting her numbers to the test, she turned to the CPF Retirement Payout Planner. Here’s how the planner helped her work through her uncertainties.
Image: CPF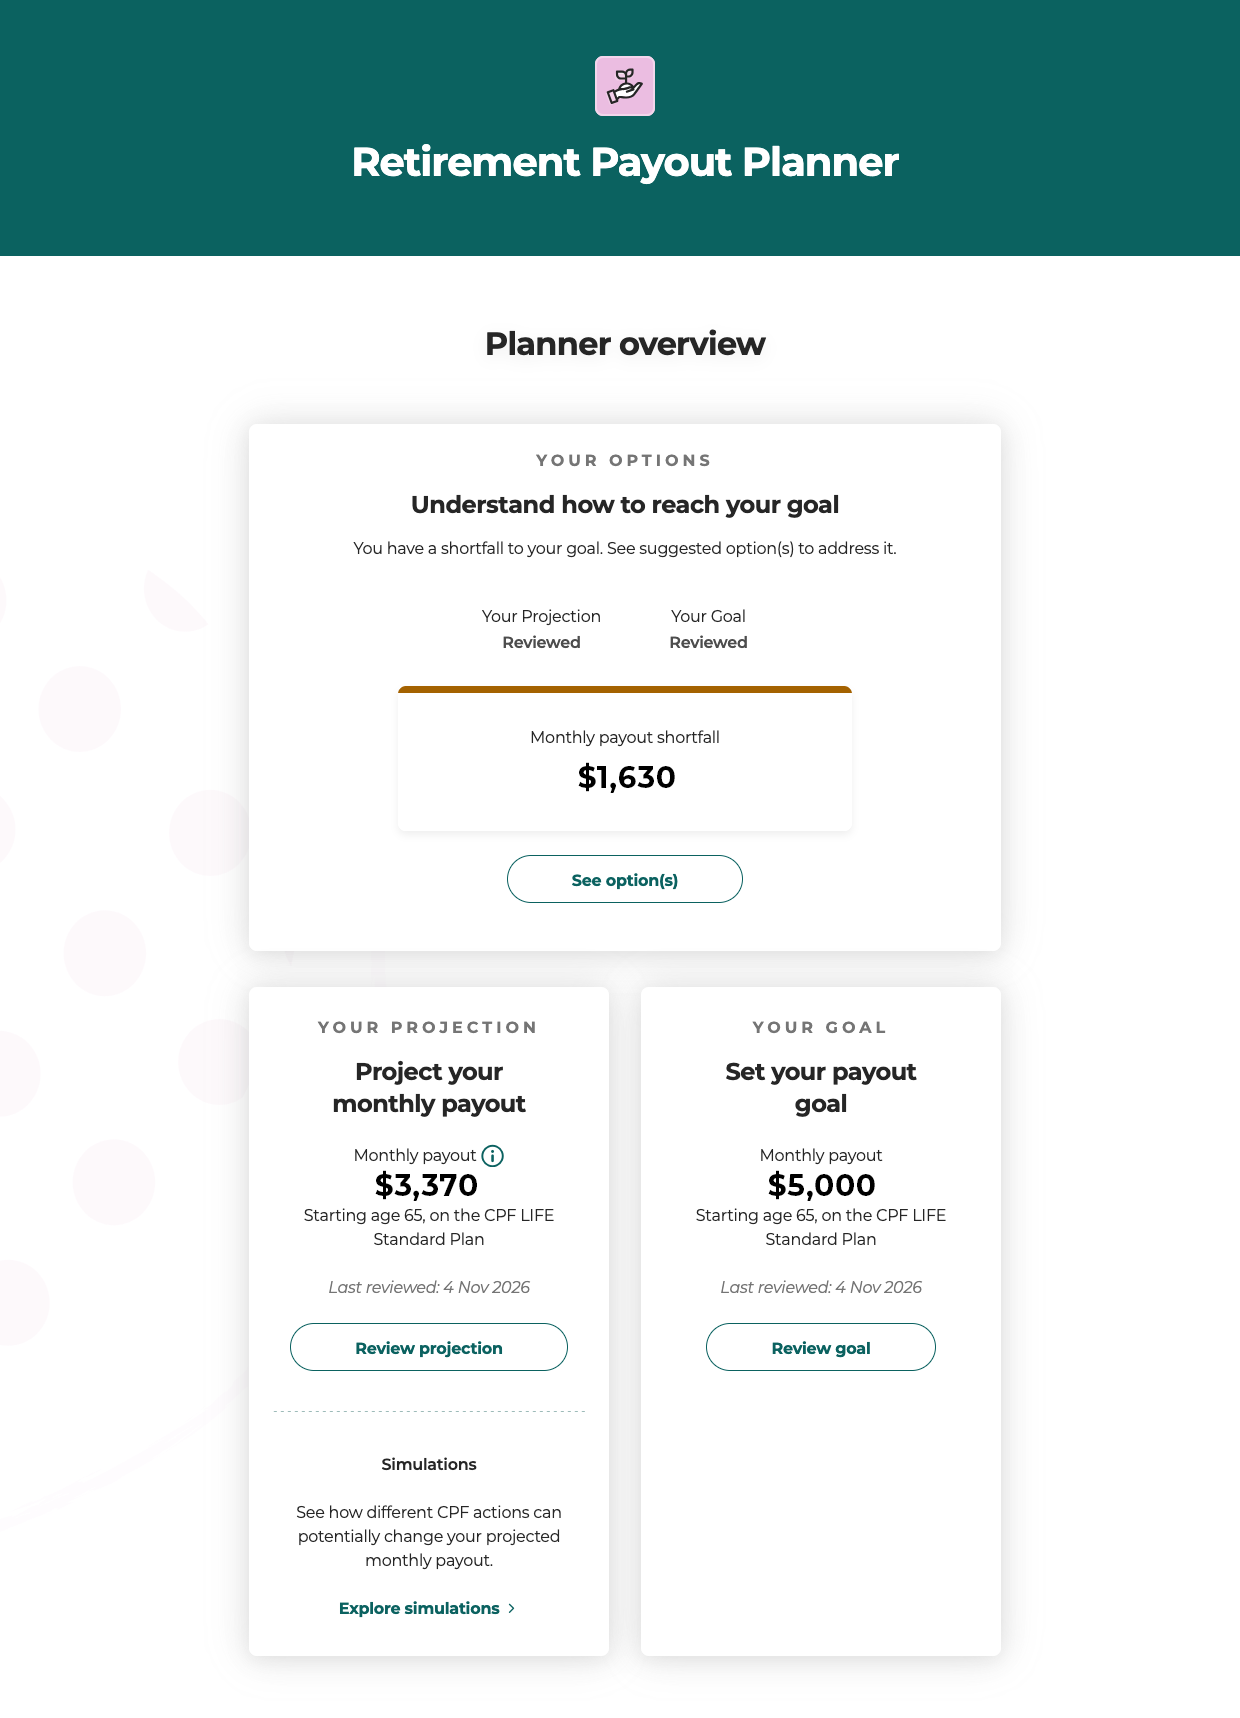
How much will your retirement lifestyle actually cost?
Having worked out how much her desired retirement lifestyle would cost each month, Sabrina estimated that she’ll need around S$3,000 to S$3,500 a month (based on today’s prices).
But with inflation to account for, Sabrina will require more to sustain her lifestyle by the time she retires. Fortunately, the planner accounts for this. With 2% inflation factored in, the planner estimates she’ll need S$5,000 a month by age 65 to maintain her desired lifestyle.
Image: CPF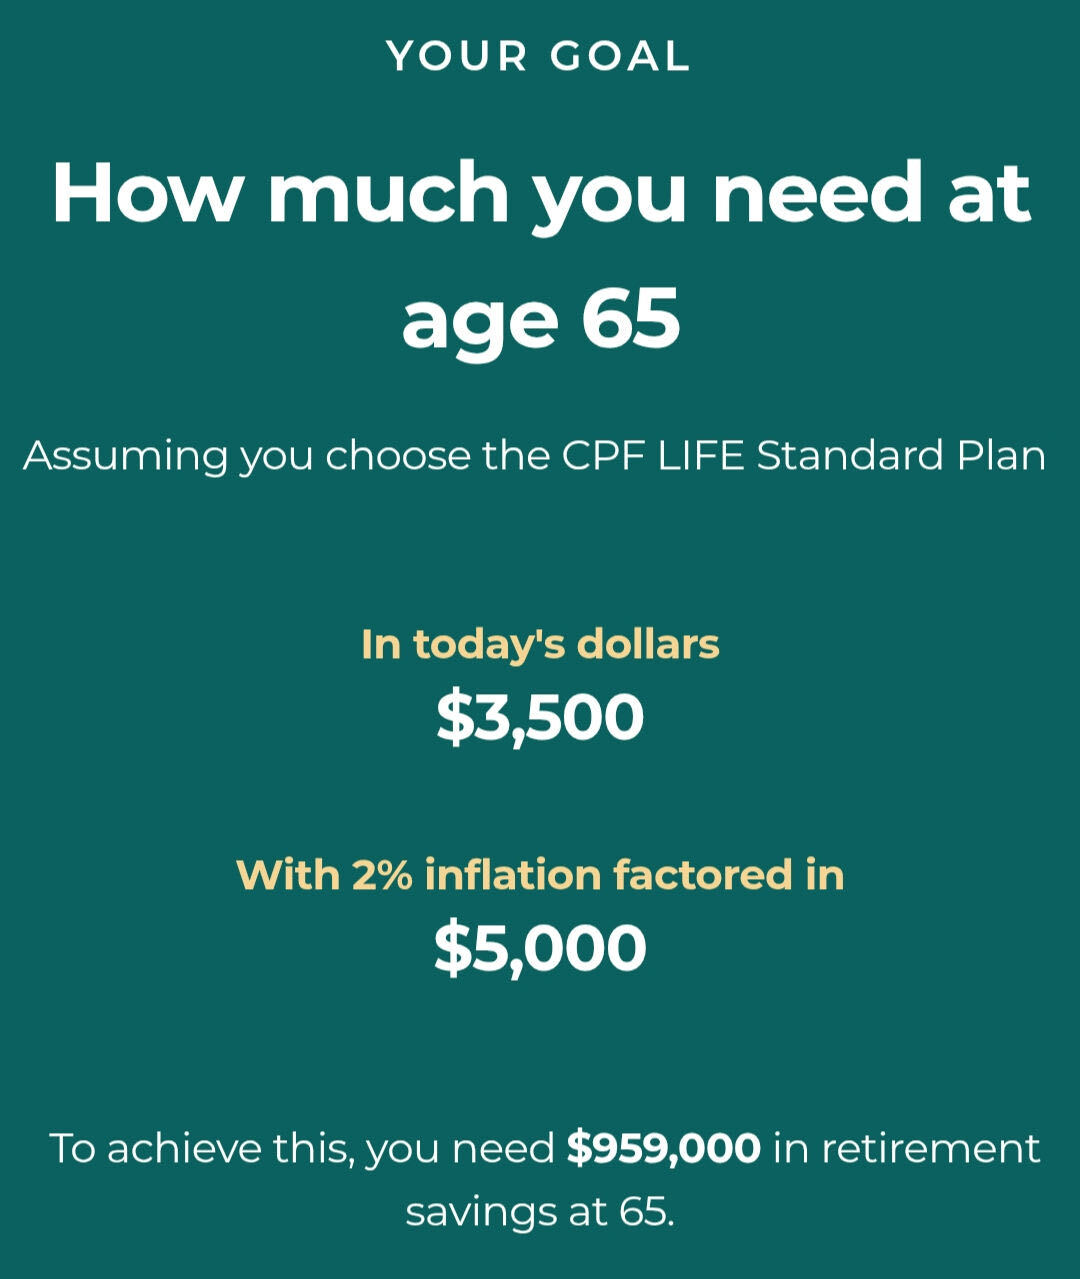
With her retirement income target in mind, she was curious to see how much her CPF payouts could cover.
Will your CPF payouts be enough to cover it?
Image: CPF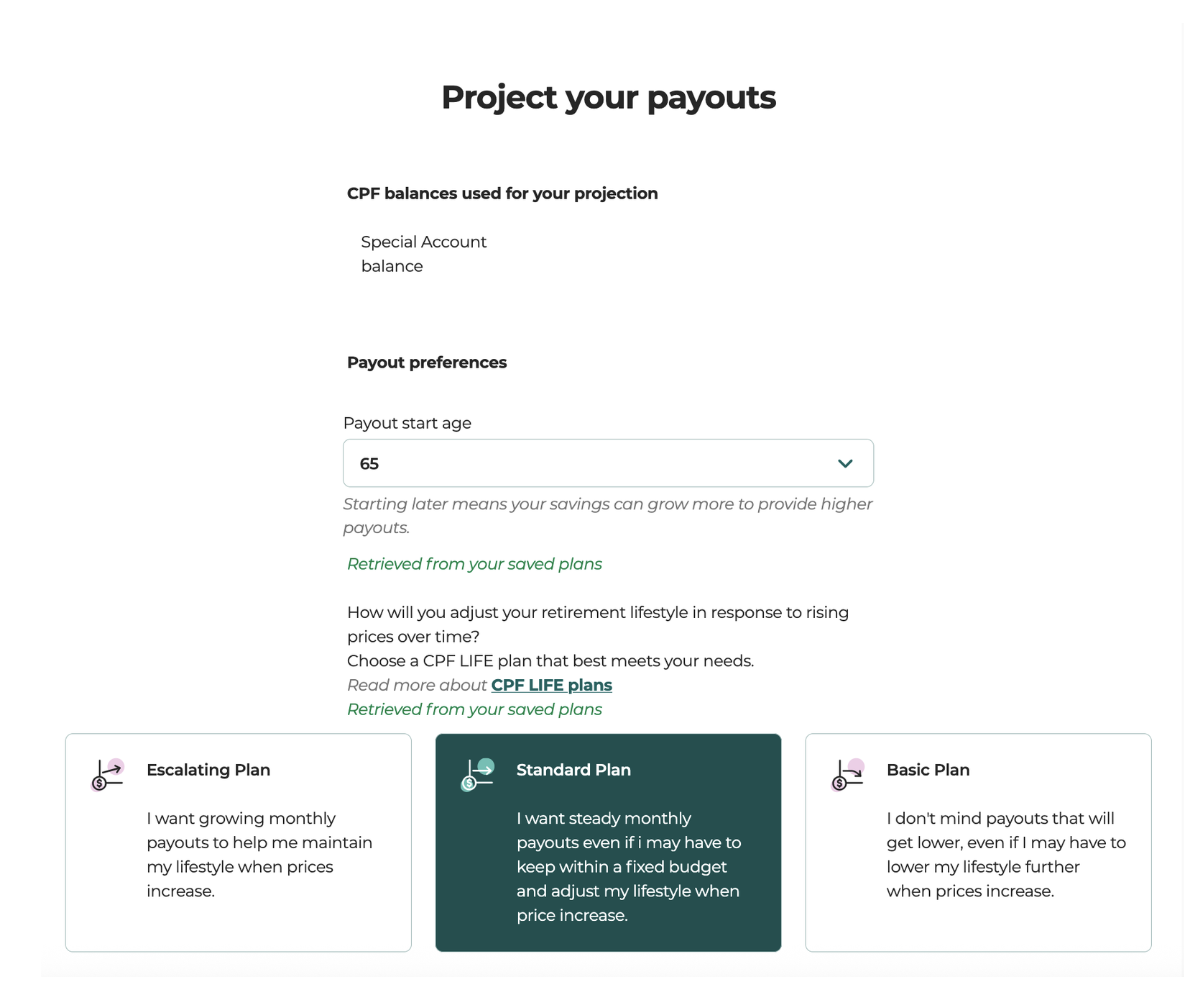
Sabrina then used the planner to estimate her monthly CPF LIFE payouts, based on her preferred payout start age and the plan that best suits her needs.
By keeping her payout start age at 65 and selecting the CPF LIFE Standard Plan, she could receive an estimated S$3,370 a month from 65. Compared with her projected retirement needs of S$5,000 a month, she now has a clearer picture of the gap she needs to bridge.
“Seeing the numbers side by side makes it real. I can finally see how much CPF will cover and how much more I need to build up through my other savings and investments. It’s a little daunting, but at least I know what I’m working towards.”
What can you do if there's a gap?
Based on these illustrative figures, Sabrina would need another S$1,630 a month to cover her projected expenses.
With retirement five to ten years away, she still has time to work towards her goal. Through the planner, she can simulate cash top-ups and OA-to-SA transfers to see how different amounts and frequency could boost her future payouts.
However, with existing expenses to manage, Sabrina decided a large one-off top-up wasn’t practical for her. Instead, she tried a smaller amount: setting aside S$500 a month for cash top-ups, which would increase her projected monthly payout to S$3,710, giving her an extra S$340 a month.
Image: CPF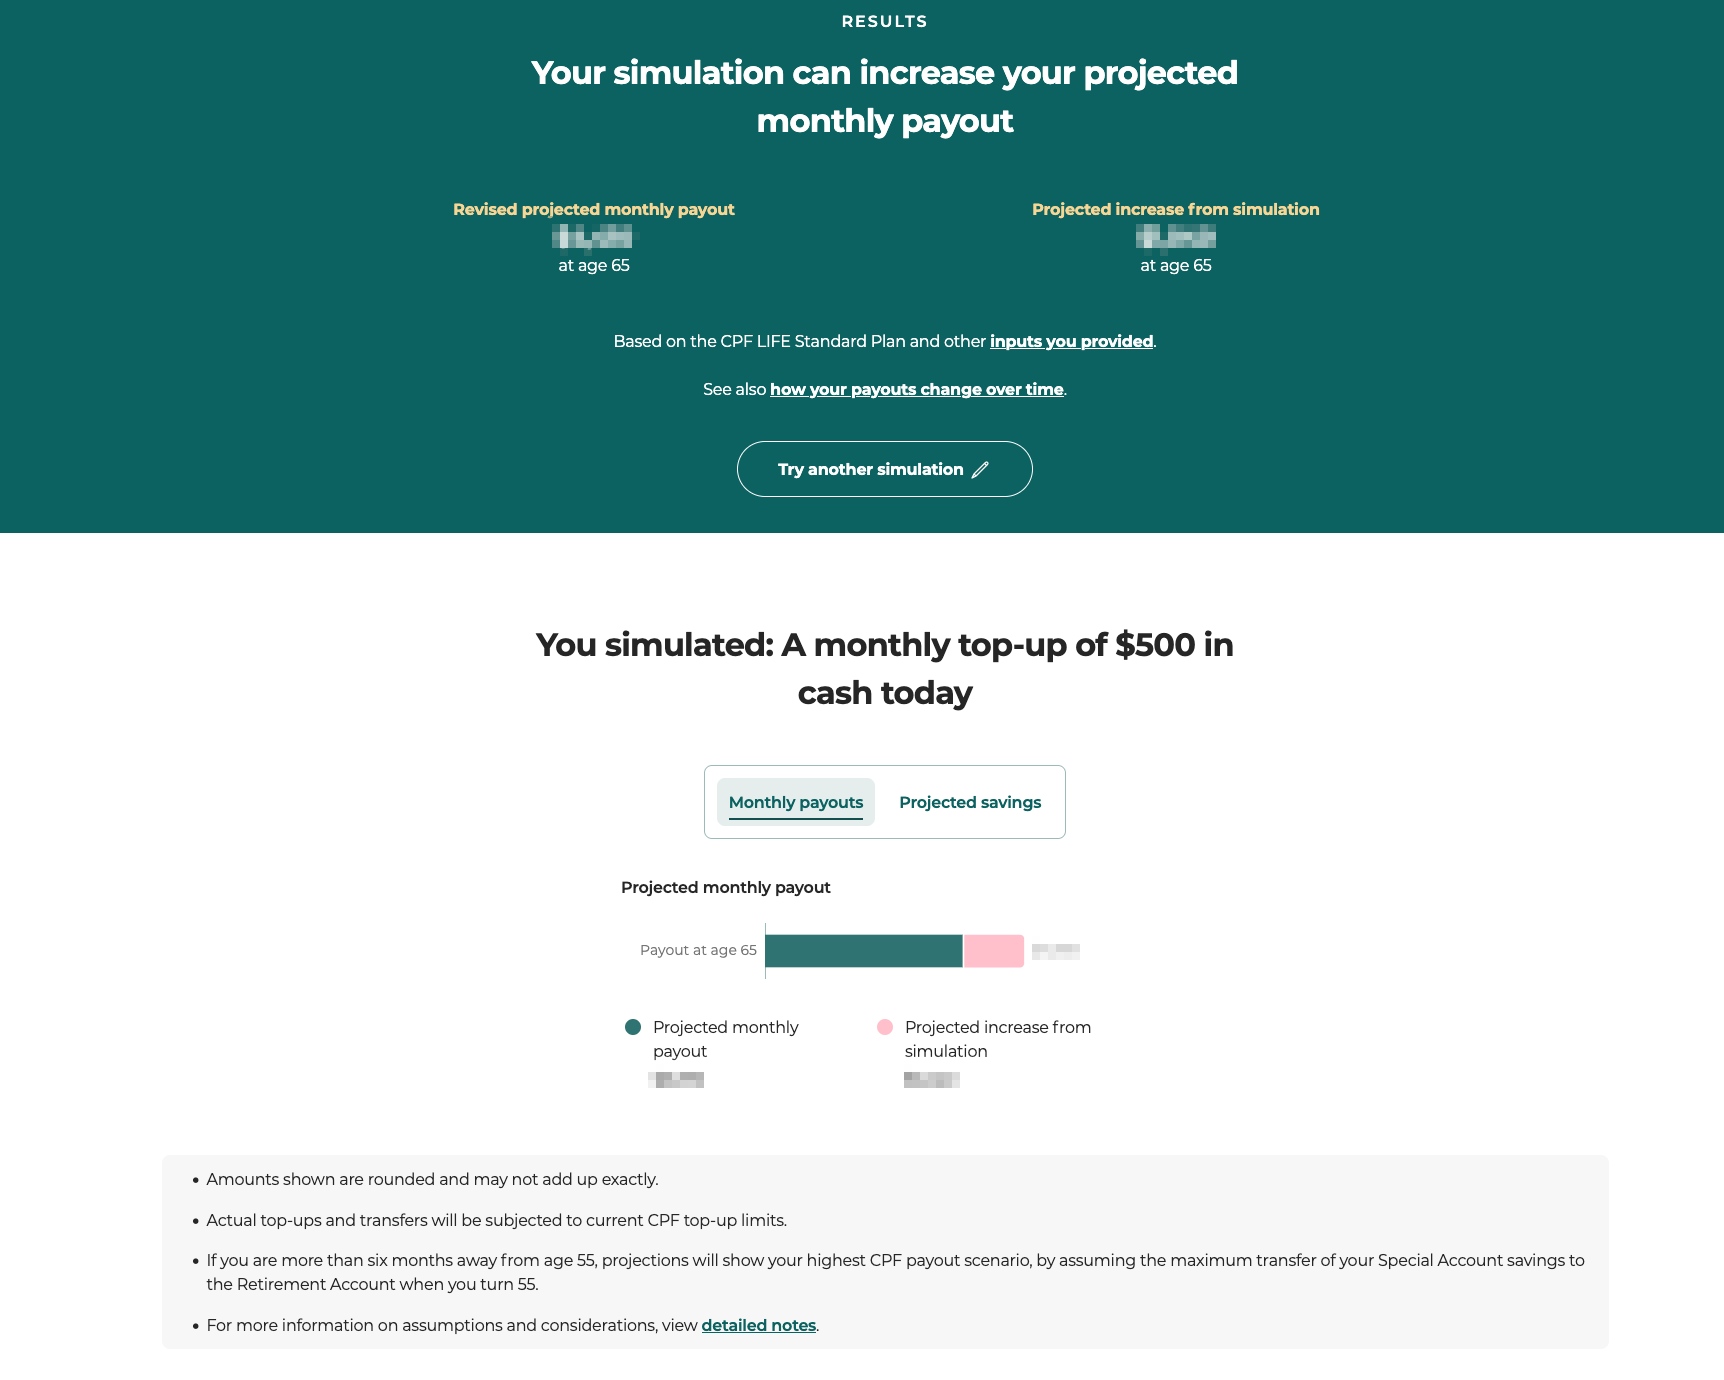
It’s a useful boost, but she’ll still need other savings and/or investments to bridge the gap. Before topping up, there are also some considerations Sabrina needs to bear in mind.
Keep some cash aside for life's unexpected costs.
Topping up your CPF for retirement is a balancing act. Like Sabrina, you’ll want to grow your retirement savings while still comfortably meeting your family’s needs and handling unexpected expenses. Before making a top-up, here are a few things to consider:
- Keep enough cash on hand. CPF savings generally can’t be withdrawn whenever you need them, so set aside enough for family commitments and unexpected expenses.
- Start with what you can afford. You don't have to top up a lump sum. Make smaller contributions that fit your budget while keeping enough cash for changing needs.
As a bonus, cash top-ups to your CPF may qualify for up to S$8,000 in annual tax relief, subject to conditions.
A useful rule of thumb: CPF top-ups should strengthen your retirement plans, not leave you financially stretched today.
Making Room for Yourself, Too
Looking after our families often means putting their needs first, leaving our own retirement plans on the back burner. Sabrina is no different. With a clearer picture of what her CPF savings could provide, she now knows what she needs to work towards.
After all, we want to care for our families without losing sight of our own future, and enjoy retirement without having to rely on our children for financial support.
You don’t need to have all the answers today. Start with the CPF Retirement Payout Planner to see where you stand and what you can do next. You can also find out more at the Ready for Life Festival roadshow at Northpoint City from 20 to 22 November.
Know someone who’s also juggling caring for their loved ones and planning for their own retirement? Send this their way!
*We’ve changed her name to protect her privacy, as this article includes details of her personal finances.
This post was written in collaboration with CPF. While we are financially compensated by them, we nonetheless strive to maintain our editorial integrity and review products with the same objective lens. We are committed to providing the best information in order for you to make personal financial decisions with confidence.
Related Articles